It's hardly an exaggeration to say that everybody knows AI is a huge booster of productivity and that it will change how we work and live in unimaginable ways. Most serious investors would agree that AI has dominated the S&P 500 and the QQQ index for the last 4 years.
I wanted to know whether this remarkable price performance is justified by the basics, like earnings growth. I wanted to know how sustainable our current pace of progress in the field of AI is, which gets at the bigger question of how sustainable is this bull market at its current valuation?
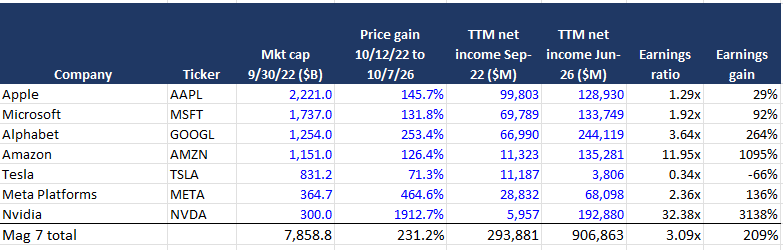
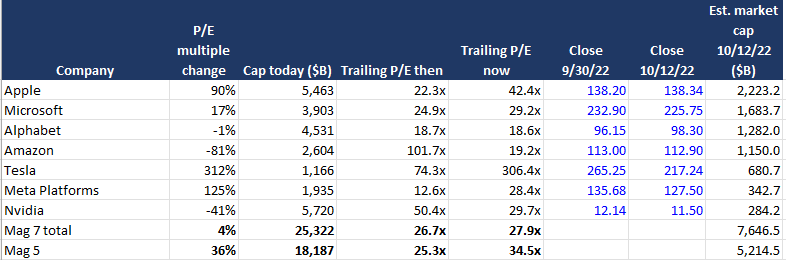
Here are all the relevant numbers used in this article
Don't worry about how all of these numbers fit together. I have already done the work and I will give you the highlights, lowlights and implications for the future.
I'll start with the primary theme based on what I found. In this bifurcated market, with the Mag 7 on one side and the other 493 stocks on the other, the Mag 7 earnings have kept up with price gains. The other 493 stocks haven't.
This takes us to the first finding: It's the other 493 stocks that we should be concerned about from a valuation standpoint, not the Mag 7.
The Mag 7 didn’t run away from the other 493 stocks. The 493 ran away from their earnings growth.
Since the market bottom in the fall of 2022, the S&P 500 has more than doubled. A big part of that gain can be attributed to the Magnificent 7: Apple (AAPL), Microsoft (MSFT), Alphabet GOOGL), Amazon (AMZN), Nvidia (NVDA), Meta Platforms (META) and Tesla (TSLA). These seven companies have gained about 220% over the course of the last 4 years. The other 493 stocks in the index are up roughly 80%.
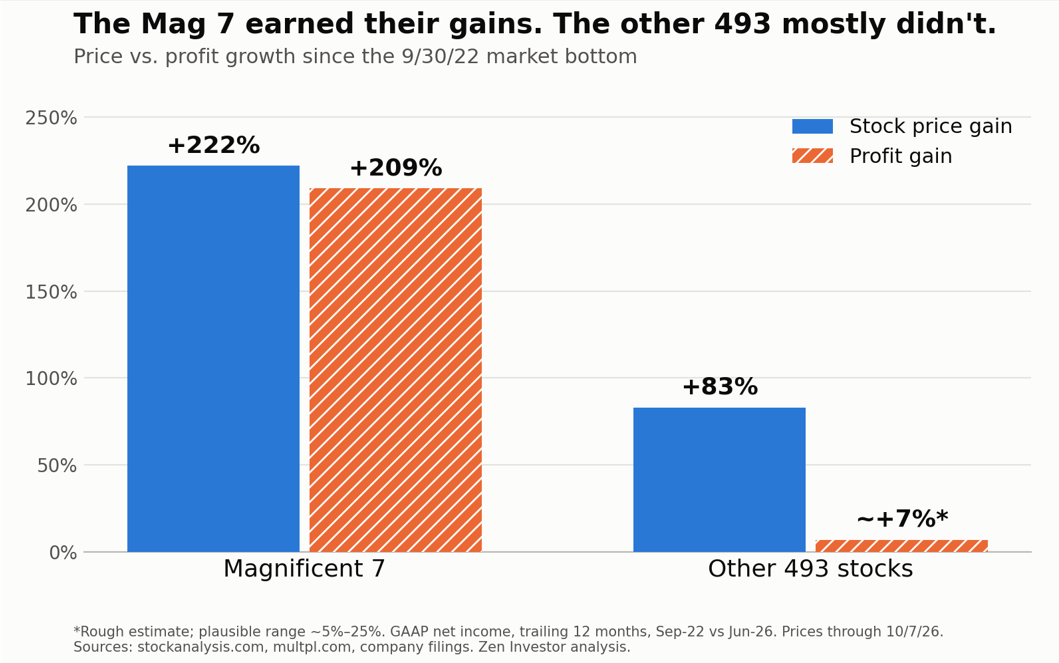
Given the fact that the Mag 7 more than tripled in market value in 4 years, while the other 493 only gained 83%, it would be easy to say that the Mag 7 are overvalued and the 493 have a lot of catching up to do. But that would not be correct. Look at this chart, which shows the price gains alongside the earnings gains for each of these cohorts.
The Mag 7 earnings hold up
Their combined profits roughly tripled over the same stretch, up about 209%. That’s close to the magnitude of their price gain. The stocks cost about the same today, relative to earnings, as they did in 2022, around 28 times what the companies earn. Nvidia does much of the work. Its profits grew more than 30x. The seven now generate about 37% of the index’s profits, up from about 17% four years ago.
The other 493 are the real surprise
Their prices rose by about 83%, but their profits barely moved by comparison. My rough estimate is that the profits for the 493 rose about 7% over those 4 years, depending on how you count. What changed is the price investors will pay for these earnings. The typical stock in that group went from about 15x earnings to about 26x.
So the “narrow leadership” worry points at the wrong group. The Mag 7 are mostly priced for what they earn. The risk is in the other 493, which have been re-valued to Mag 7 P/Es without earning Mag 7 profits. If those multiples come back toward their old levels, the index feels it even if the Mag 7 keep delivering.
Final thoughts
In a market that is so dominated by so few stocks, the risks are higher than usual. An earnings miss, or a guidance trim by one or more of the Mag 7 cohort could quickly send the entire S&P 500 index down by 10% or more.
But it may turn out that more damage would be done to the other 493, given their high valuations. My view is that the AI trade will be with us for a long time, and the benefits in terms of increased productivity will be distributed amongst the 493 as well as the Mag 7.
I do, however, worry about the valuations for the 493. As the data shows, they are now priced as dearly as the Mag 7, without producing Mag 7-like profits. It's a cautionary tale that we should all be aware of as we allocate our assets between these two distinct parts of the market.