
Superior Group [SGC]
SGC is an under-the-radar micro-cap firm, founded in 1920 and is headquartered in Seminole, Florida. It is engaged in designing, manufacturing, and distributing uniforms to major domestic retailers, foodservice chains, transportation, and other service industries.
It provides customer-specific uniform eStores and call center operations for the medical and health fields, and for industrial, commercial, and leisure businesses.
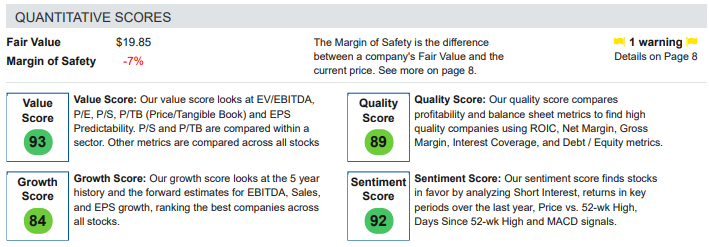
SGC is the newest addition to the Zen High Quality model portfolio, which is up 21.8% year-to-date. SGC has outperformed the S&P 500 by 23.3% in the past year, and it has outperformed its sector by 11.9%.
SGC’s biggest rival is Cintas [CTAS], a $32 Bn behemoth that dominates the field. SGC is quietly taking market share from CTAS. SGC is more nimble than CTAS and they are able to focus on the needs of their health care customers and give them the protective gear they so desperately need.
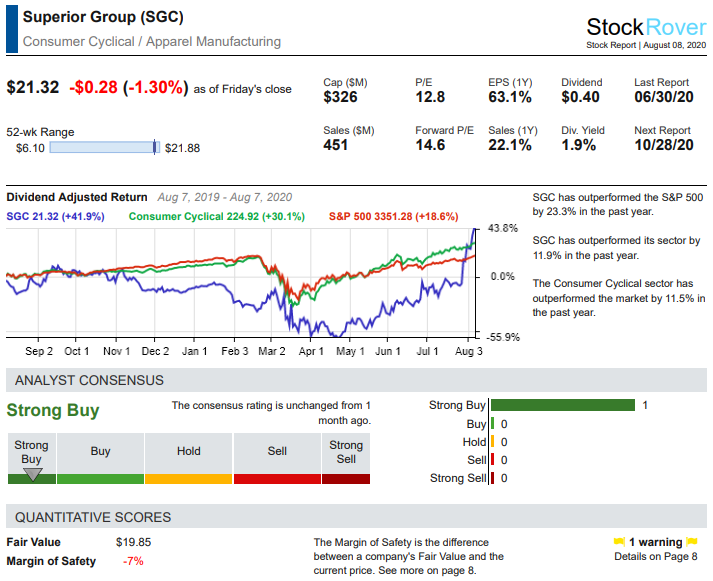
SGC earns high scores for quality, value, growth, and sentiment.
Valuation metrics
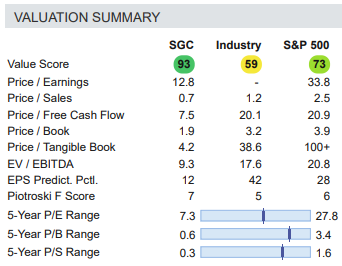
With a P/E of 12.8 and a P/S of 0.7, SGC is very undervalued, even though it has been on a tear recently. It’s not too late to buy this stock.
SGC scores well against its peer group
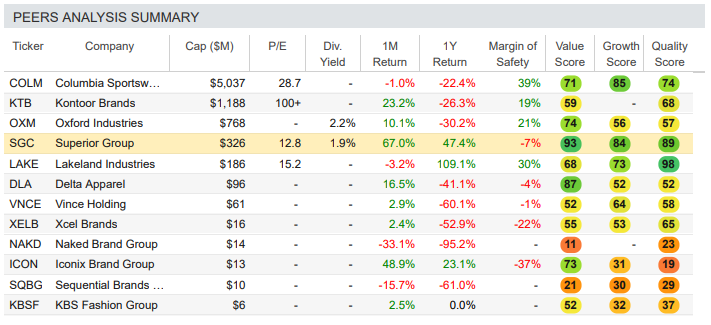
(CTAS is not listed as a peer due to the way StockRover categorizes companies in their database.)
Profitability metrics
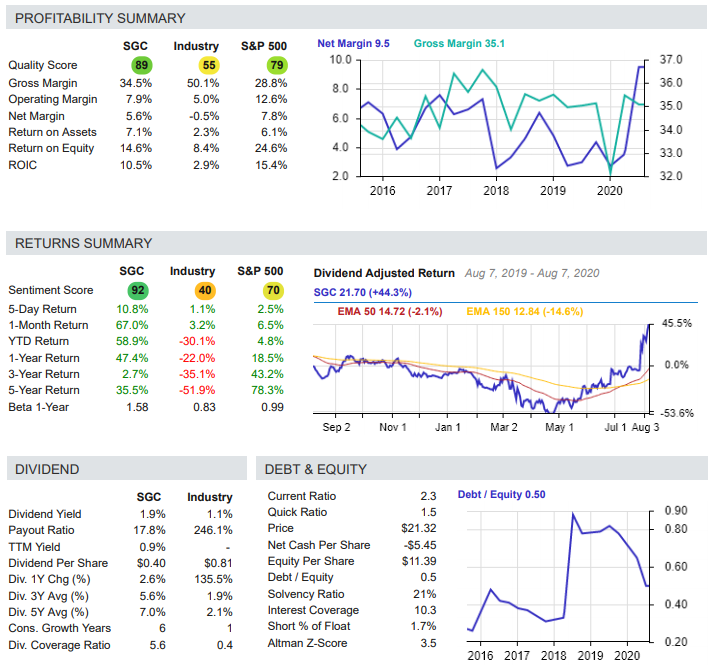
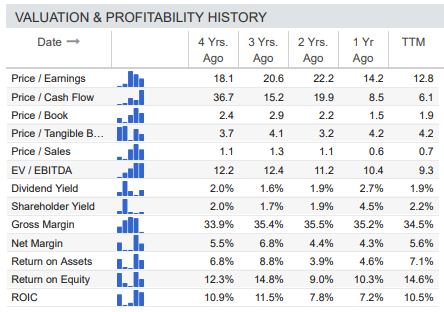
Profitability is the only weak spot for SGC. As they gain market share versus the competition, profitability should improve.
Earnings surprises and risk metrics
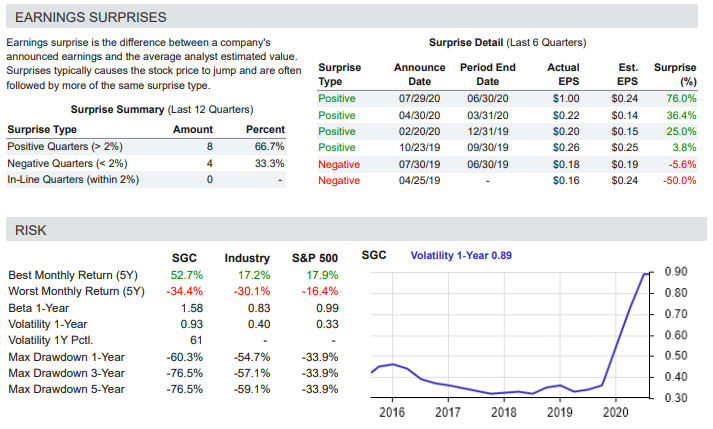
SGC has put up great numbers lately. Maybe that’s why the stock is on a tear. But there’s more upside to come because the stock is still undervalued.
Final thoughts
I think SGC has a lot more room to grow, in terms of market share, profitability, and price. This is a high quality company with lots of potential. It’s cheap because they cut their dividend, but that’s already baked into the current price of $21.32. Dividend investors sold it hard after the cut, but now it’s a value and growth story. Perfect for investors who are looking for high quality stocks at bargain-basement prices.